Date : 01/07/2026 |
Home Loan vs Renting in India (2026): Which Builds More Wealth? A Financial Analysis by 85inches Realty Pvt. Ltd.
By Research Team | 85inches Realty Pvt. Ltd.
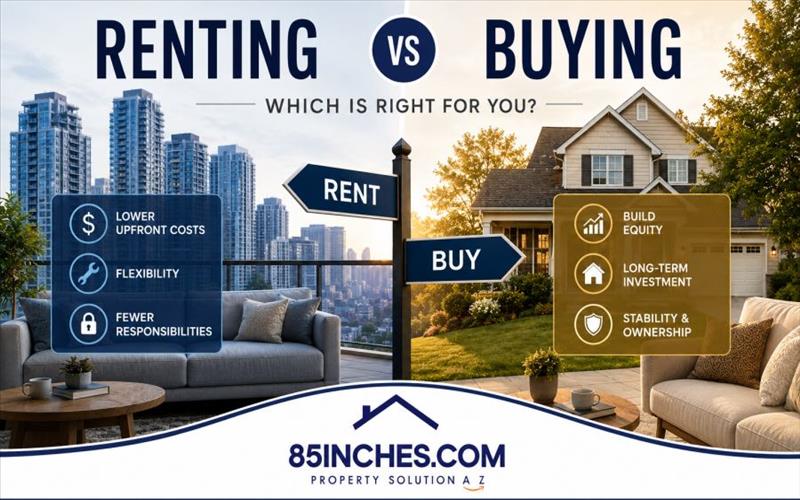
Home Loan vs Rent: Which Is the Smarter Financial Decision?
Buying a home is one of the biggest financial decisions most
Indians will ever make. For many families, owning a house represents stability,
achievement, and long-term security. With attractive home loan offers and
flexible repayment options, purchasing a home has become more accessible than
ever.
But an important
question remains:
Is buying a home with a long-term loan always the best
financial decision?
At 85inches Realty Pvt. Ltd., we believe every property purchase
should be backed by careful financial analysis—not just emotions. This research
article explores whether renting and investing the difference could potentially
generate greater long-term wealth than purchasing a home through a loan.
Understanding the Cost of Buying a Home
Let's consider a typical example.
Property Value: ₹40,00,000
Initial Investment
Down Payment (15%) – ₹6,00,000
Stamp Duty & Registration – Approx. ₹2,50,000
Brokerage, Legal & Documentation – ₹50,000
Interior, Furniture & Moving Expenses – ₹1,00,000+
Total Initial Investment: Approximately ₹10,00,000
If the remaining ₹34–35 lakh is financed through a home loan
at approximately 9% for 20 years, the monthly EMI would be around ₹31,500.
Over two decades, this becomes a significant financial
commitment that affects savings, investments, and lifestyle choices.
The Renting + Investing Strategy
Now consider an alternative approach.
Rent the same property for approximately ₹15,000 per month.
Compared to the EMI:
Monthly Saving: Around ₹16,500
Initial Capital Preserved: Approximately ₹10 lakh
Instead of paying a higher EMI, invest both:The monthly
savings through a disciplined SIP.
The upfront ₹10 lakh as a long-term investment and The Power
of Compounding
If the monthly investment of ₹16,500 earns:
At 12% Annual Return
Potential corpus after 20 years:
Approximately ₹1.6 Crore
At 15% Annual Return
Potential corpus:
Around ₹2.4 Crore
Now consider the initial ₹10 lakh invested for the same
period.
At 12%:
Nearly ₹97 lakh
At 15%:
Around ₹1.6 Crore
Combined Wealth Creation
The total investment portfolio could potentially grow to
₹2.5 crore to ₹4 crore, depending on investment performance.
(Illustrative calculations only. Actual returns depend on market
performance and investment discipline.)
How Does Real Estate Appreciation Compare?
Residential real estate has historically appreciated over
long periods, although returns vary significantly by city, locality,
infrastructure development, and market cycles.
A ₹40 lakh property appreciating steadily could become
substantially more valuable over two decades. However, owners should also
account for:
Maintenance expenses, Society charges, Renovation costs,
Property taxes, Liquidity considerations
Market cycles,
Property appreciation should therefore be evaluated
alongside the total cost of ownership.
Hidden Costs of Buying a Home
Many buyers focus only on the EMI and overlook additional
ownership costs.
These may include:
Home maintenance and repairs, Society maintenance charges,
Property taxes, Interior upgrades
Insurance, Registration expenses, Opportunity cost of
blocked capital
These expenses can materially affect the overall financial
outcome.
Advantages of Renting
Renting can provide greater flexibility, particularly for
young professionals and investors.
Benefits include:
Lower monthly cash outflow, Greater career mobility, higher liquidity,
Easier relocation
More capital available for diversified investments, Reduced
financial stress during uncertain income periods
Advantages of Buying a Home
Buying a home also offers meaningful benefits beyond
financial returns.
These include:
Long-term residential security, Freedom to customize your
property, Protection from future rent inflation, Asset ownership, Potential
appreciation over time, Emotional satisfaction of owning a home, For many
families, these non-financial benefits are highly valuable.
What Should Investors Do?
The right choice depends on your objectives.
Renting may be suitable if you:
Frequently relocate for work, Prioritize wealth creation
through investments, Want maximum financial flexibility, Have strong investment
discipline, Buying may be suitable if you:, Plan to stay in one location for
many years, Value long-term residential stability, Purchase in a high-growth
micro-market, Have sufficient emergency savings and manageable EMIs.
Research Team's Perspective
At 85inches Realty Pvt. Ltd., we encourage buyers to make
data-driven decisions rather than emotional ones.
A home should ideally be purchased when:
The EMI comfortably fits within your financial plan and when
You have adequate emergency reserves,
The property is located in a fundamentally strong growth
corridor.
The purchase aligns with your long-term lifestyle and
investment goals.
For investors, wealth is often created through a balanced
combination of real estate, equities, mutual funds, and other diversified
assets, rather than relying on a single investment class.
Conclusion -
There is no universal answer to the question of Home Loan vs
Renting.
For some people, homeownership provides unmatched peace of
mind and long-term stability.
For others, renting while investing consistently may result
in a larger investment portfolio over time.
The smartest financial decision is the one that aligns with
your income, career plans, risk tolerance, and long-term objectives.
At 85inches Realty Pvt. Ltd., our Doctrin is to help every
buyer and investor make informed, research-backed property decisions that
support sustainable wealth creation.
About - 85inches
Realty Pvt. Ltd.
85inches Realty Pvt. Ltd. is a Mumbai based research-driven
real estate advisory company specializing in:
Property Investment Advisory, Property Inspection &
Valuation, AI-Powered Property Analysis, Real Estate Market Research, Commercial
& Residential Consulting, Investment Corridor Research, Home Loan &
Financial Advisory, Legal Due Diligence , NRI Investment Support
Website: www.85inches.com
Email: helpdesk@85inches.com
Phone: +91 9205031305
Disclaimer
The 85inches Realty clearly disclaims all liability in respect to actions taken or not taken based on any or all the contents of this Blog. The content of this blog is collation of data from various sources and is provided only for information purpose only and 85inches Realty does not canvass the particulars, information, brand or any other materials mentioned in the blogs nor does it obtain any monetary benefit from the same.The 85inches Realty shall in no circumstance be held liable for any expense, loss or damage including, without limitation, direct, indirect or consequential loss or damage, or any other expense, loss or damage whatsoever arising from the use of data, information, interpretation, judgement or opinion arising out of or in connection with the use of this Blog. Reader is advised to read and apply his/ her intellect and discretion in this regards.
Recent Blog
Popular Blog
The Impact of Infrastructure Development on Varanasi Real Estate ?
15/04/2025 | 1997
Why do you need to take home inspection services before buying it ?
15/04/2025 | 1956
How can housing societies tackle non-payment of maintenance charges?
16/06/2025 | 1857